Same Day ACH Tops $1.1 Trillion: What Record Growth Means for Lenders

Same Day ACH Tops $1.1 Trillion

What the Latest Growth Mean for Lenders

Borrowers have become accustomed to instant access. They can order products online, transfer money between accounts, and receive payments within seconds. As these expectations continue to shape consumer behavior, they are increasingly influencing the lending industry as well.

When a loan is approved, borrowers no longer compare their experience solely against other lenders. They compare it against every other digital experience in their lives. Waiting days for funds to arrive can feel outdated, particularly when the need for funds is urgent.

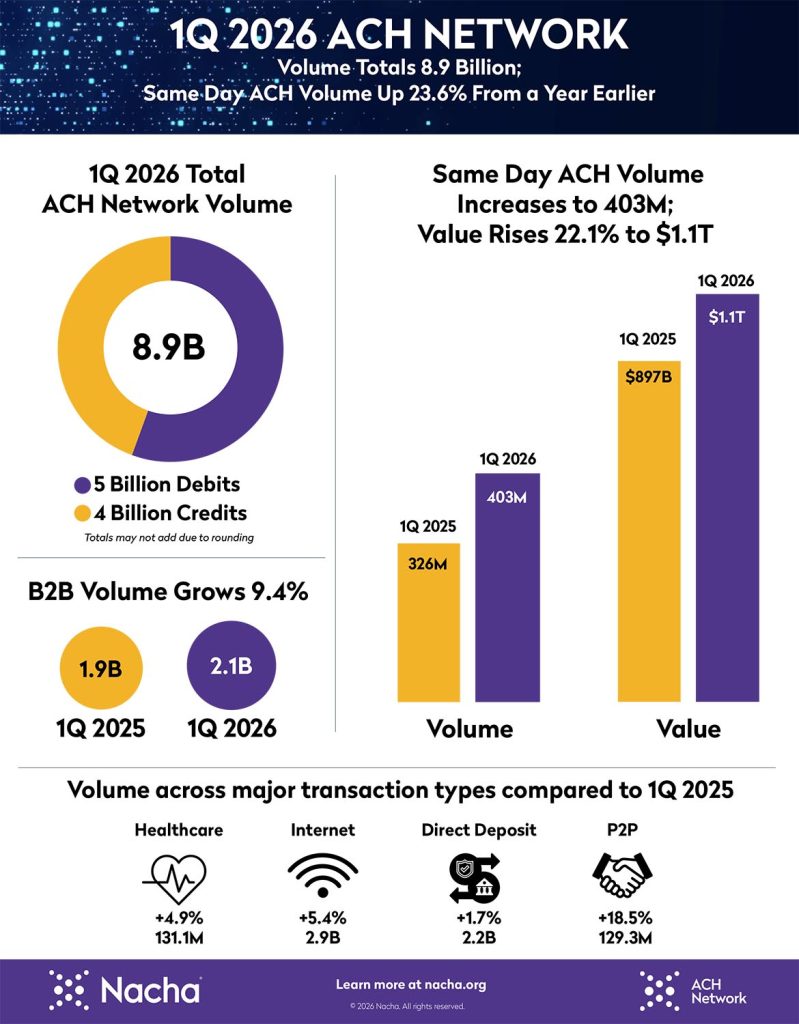
Recent ACH Network growth data suggests that financial institutions and businesses are responding to this demand for faster payments. During the first quarter of 2026, Same Day ACH volume increased 23.6% year-over-year to 403 million payments, while the value of those payments reached $1.1 trillion, an increase of 22.1%.

These numbers demonstrate that faster payment capabilities are becoming increasingly important across the financial ecosystem, including lending.

Same Day ACH volume reached 403 million payments during the first quarter of 2026, while payment value exceeded $1.1 trillion for the second consecutive quarter.

For many borrowers, access to funds is the most important part of the lending experience.

A streamlined application process and quick approval lose much of their value if borrowers must wait days to receive their money. Whether funding is needed for emergency expenses, home repairs, vehicle repairs, medical bills, or short-term cash flow needs, delays can negatively impact borrower satisfaction.

Faster funding can help lenders:

  • Improve borrower satisfaction
  • Increase repeat borrowing activity
  • Strengthen customer retention
  • Differentiate themselves in a competitive market
  • Reduce funding-related support inquiries

As borrower expectations continue to evolve, funding speed has become an important part of the overall customer experience.

While much attention has been focused on real-time payment networks such as RTP and FedNow, Same Day ACH continues to experience significant growth.

One reason is accessibility.

Most financial institutions already participate in the ACH Network, making Same Day ACH a practical option for many lenders that want to accelerate funding without implementing entirely new payment workflows.

Same Day ACH can help lenders:

  • Deliver funds faster than traditional ACH
  • Improve operational efficiency
  • Reduce delays caused by batch processing
  • Provide more predictable settlement timing
  • Expand funding options for borrowers

For many lending organizations, Same Day ACH serves as an effective bridge between traditional ACH processing and real-time payment solutions.

The first-quarter ACH data also showed strong growth in business-to-business payments and continued expansion across internet-based transactions.

This broader growth reflects an ongoing migration away from paper-based payment methods and toward digital payment experiences.

For lenders, this trend extends beyond loan funding. ACH remains a critical tool for:

  • Recurring loan payments
  • Account verification processes
  • Consumer disbursements
  • Collections and repayment programs
  • Settlement and reconciliation operations

As lending becomes increasingly digital, ACH continues to provide the foundation for many borrower-facing payment experiences.

The continued growth of Same Day ACH provides an opportunity for lenders to evaluate whether their payment strategy aligns with borrower expectations.

Consider the following questions:

  • How quickly can borrowers receive funds after approval?
  • Are funding delays creating friction in the borrower experience?
  • Could Same Day ACH improve customer satisfaction or retention?
  • Are there opportunities to incorporate RTP or FedNow alongside existing ACH processes?

Lenders that proactively evaluate their payment capabilities today will be better positioned to meet the expectations of tomorrow’s borrowers.

The first quarter of 2026 highlighted the continued strength of the ACH Network, but the most significant takeaway for lenders may be the ongoing growth of Same Day ACH.

As borrowers increasingly expect faster access to funds, lenders must balance speed, efficiency, risk management, and operational simplicity. Same Day ACH continues to provide a practical solution that helps bridge those competing priorities.

At Viking, solutions such as VIKExpress, VIKEdge, and VIKEngage help lenders modernize payment operations, improve funding experiences, and maintain visibility into transaction performance as payment expectations continue to evolve.

May 7, 2026

About John O’Shea

He is a former founder and owner of Triad Financial Services and has served in similar roles at GMAC/Residential Funding, AllianceOne and ICT Group (now Sykes). He has performed for 28 years as a senior executive in the ARM, Customer Contact and BPO markets. He is a graduate of St. Olaf College.

Bigger Possibilities Await.

Contact Us


Read More

Upcoming NACHA Rules Changes: Implications for Originators and Merchants

Upcoming NACHA Rules Changes

Implications for Originators and Merchants

As a payment compliance specialist, it is critical to stay abreast of the latest NACHA (National Automated Clearing House Association) rule changes. Two sets of amendments are set to take effect this year—on June 21 and October 1, 2024. Some of these changes will impact originators and merchants significantly, emphasizing the need for proactive adjustments to compliance and operational strategies.

June 21, 2024: Minor Rules Topics

The first wave of changes focuses on minor rule topics. Minor changes to the Rule have little to no impact on ACH participants and no significant processing financial impact.

  1. General Rule /Definition of WEB Entries– The updated NACHA rule clarifies the use of WEB entries, which are transactions initiated by a consumer over the internet or a wireless network. The new definition eliminates confusion by specifying that all consumer-to-consumer credits must use the WEB SEC code, regardless of the internet or wireless network being the method of initiation.
  2. Definition of Originator– The updated rule provides a clearer definition of an Originator, stating that it is the party authorized by the Receiver to credit or debit the Receiver’s account at the RDFI (Receiving Depository Financial Institution). This clarification helps in precisely identifying the responsible entity in a transaction, thus reducing ambiguities and potential disputes between parties involved in ACH transactions
  3. Originator Action on Notice of Change– This rule requires Originators to take prompt action upon receiving a Notice of Change (NOC) from the RDFI. The NOC indicates necessary corrections to the information within an ACH entry. Originators must make the specified changes within six banking days or before the next entry, whichever is later.
  4. Data Security Requirements– The updated rule extends the data security requirements to all non-consumer Originators, Third-Party Service Providers, and Third-Party Senders.
  5. Use of Prenotification Entries– The revised rule on prenotification entries provides clarity on their use and the handling of responses from RDFIs. Prenotification entries are optional but recommended for verifying account information before initiating live transactions. Originators can use these entries to ensure that account details are correct, reducing the risk of errors and rejected transactions. If an RDFI responds to a prenotification with a NOC, the Originator must address the indicated issues promptly
  6. Clarification of Terminology – Subsequent Entries– The rule clarifies the term “Subsequent Entries,” referring to entries that follow an initial authorization. These can be initiated by the consumer through actions such as phone calls or online requests. The updated rule allows greater flexibility in the use of Standard Entry Class (SEC) codes for these subsequent entries, accommodating various methods of initiation and ensuring that authorization requirements are met appropriately

October 1, 2024: Risk Management Topics

The second set of changes, effective October 1, centers around risk management, reflecting NACHA’s ongoing efforts to enhance the security and reliability of the ACH Network:

  1. Codifying Expanded Use of Return Reason Code R17– The updated rule codifies the expanded use of Return Reason Code R17 to enhance the identification and management of fraudulent activities. This rule includes the following specifics:
    • R17 + “QUESTIONABLE”: The addition of the word “QUESTIONABLE” in the return addenda record signifies a potential fraud alert on the receiving bank account. This helps financial institutions quickly identify transactions that may require further scrutiny for fraud
    • Impact on Unauthorized Return Rates: These returns will not be counted in unauthorized return rates, thus not affecting the metrics used to evaluate the frequency of unauthorized transactions
    • This new Rule also includes references to a newly defined term, False Pretenses: The inducement of a payment by a Person misrepresenting (a) that Person’s identity, (b) that Person’s association with or authority to act on behalf of another Person, or (c) the ownership of an account to be credited.”
      This definition covers common fraud scenarios such as Business Email Compromise (BEC), vendor impersonation, payroll impersonation, and other payee impersonations, and complements language on “unauthorized credits” (account takeover scenario). It does not cover scams involving fake, non-existent or poor-quality goods or services.
    • Expanded Use of ODFI Request for Return/R06–This rule expands the circumstances under which an Originating Depository Financial Institution (ODFI) can request a return of an entry using Return Reason Code R06 (Return per ODFI’s Request). This expansion aims to provide more flexibility and tools for ODFIs to manage erroneous or problematic entries, ensuring better correction of mistakes and reducing potential risks associated with such entries
    • Ensure your loan management and payment processing systems are updated for NACHA’s new R17 rule. This rule allows RDFIs to use Return Reason Code R17 with the descriptor “QUESTIONABLE” in the Addenda Information field to flag transactions that may be suspicious or fraudulent. Updating your systems will help differentiate these returns from routine account errors and maintain compliance with NACHA’s standards.
  2. Additional Funds Availability Exceptions– The rule introduces new exceptions to the funds availability requirements, allowing RDFIs more time to investigate suspicious transactions before making funds available to the account holder. This extension is critical in scenarios where there is a high likelihood of fraud, enabling RDFIs to ensure that the transaction is legitimate before releasing the funds. This change aims to reduce the risk of fraudulent withdrawals and losses for both the financial institution and the account holder
  3. Timing of Written Statement of Unauthorized Debit (WSUD)– The rule modification allows for greater flexibility in the timing of signing a WSUD. Specifically, it permits the WSUD to be signed and dated by the Receiver on or after the date the unauthorized debit entry is presented, even if the debit has not yet posted to the account. This change simplifies the process for receivers to dispute unauthorized debits and facilitates quicker resolution of such issues​
  4. RDFI Must Promptly Return Unauthorized Debit– This rule mandates that Receiving Depository Financial Institutions (RDFIs) must promptly return any unauthorized debit entries once they are identified. This requirement ensures that unauthorized debits are addressed quickly, minimizing the impact on the account holder and reducing the potential for further fraudulent activity. It emphasizes the responsibility of RDFIs to act swiftly in protecting their customers’ accounts from unauthorized transactions

For further details on these rule changes, visit NACHA’s official website on minor rules topics and risk management topics.

Preparing for Compliance

For originators and merchants, preparation is key to ensuring compliance with these new rules:

  • Review and Update Systems: Ensure that all payment processing systems are updated to align with the new data specifications and validation requirements.
  • Train Staff: Conduct comprehensive training sessions for relevant staff to familiarize them with the new rules and their implications.
  • Enhance Fraud Detection: Invest in advanced fraud detection and prevention technologies to meet the updated standards.
  • Audit Third-Party Relationships: Conduct thorough audits of third-party sender relationships to ensure compliance with the new risk management requirements.

By proactively addressing these changes, originators and merchants can mitigate risks, ensure compliance, and continue to facilitate secure and efficient ACH transactions.

June 4, 2024

About Adam Garrett

He has spent almost 20 years building successful merchant acquiring programs and is a proven sales leader who brings his expertise in team management, business development, and strategic planning to Viking Payments. He received his MBA from the University of Texas at Dallas, and his BS at Missouri State University.

Bigger Possibilities Await.

Contact Us


Read More